10-Hour Houses, Mortgage Rate Whiplash, and Why Millennials Just Killed the Formal Dining Room
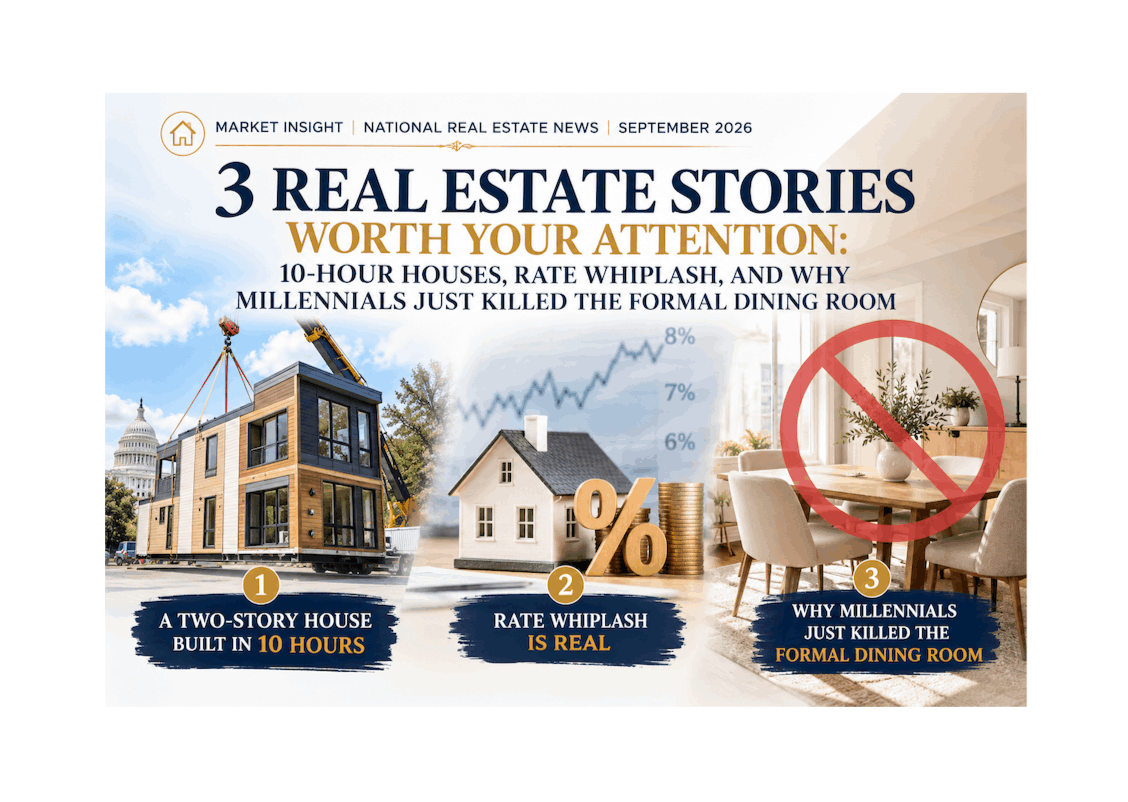
They Built a Two-Story House on the National Mall in 10 Hours
Tourists in Washington, D.C. got a surprise this week: about eight manufactured homes assembled right between the Washington Monument and the Capitol, as part of HUD's sixth annual Innovative Housing Showcase. A two-story manufactured home that was built in just 10 hours on-site - a demonstration of exactly how fast modern construction technology has become.
The showcase featured manufactured, 3D-printed, and modular homes alongside genuinely novel engineering - including a tool from Oak Ridge National Laboratory that uses lasers to create heat-maps for more evenly spread foundations. As Lesli Gooch, CEO of the Manufactured Housing Institute, put it: "Every year we have brought homes to the Mall that challenge long held assumptions about what manufactured housing can be, and this year is truly a game changer for the industry thanks to the 21st Century ROAD to Housing Act."
That's not an accident of timing. One home on display wasn't built on a traditional steel chassis - a direct result of the housing law Christina Chorna covered in a previous blog post, which eliminated the outdated chassis requirement from the federal definition of manufactured housing. Removing that requirement could reduce manufactured home costs by $5,000 to $10,000 - and the National Mall showcase is the clearest public demonstration yet of what that actually looks like built out.
Why This Matters for Connecticut: HUD Secretary Scott Turner said the goal is to 'showcase the brilliance of the American people' while addressing the national housing shortage head-on. For Connecticut —-where new construction has struggled to keep pace with demand across Milford, Norwalk, and New Haven - faster, cheaper, code-approved manufactured and modular housing represents a genuine supply-side opportunity, not a downgrade. The stigma around manufactured housing is rapidly becoming outdated right along with the chassis requirement that used to define it.
Mortgage Rate Whiplash Is Real - Here's How to Budget for It
If mortgage rates feel like they've been on a rollercoaster lately, that's because they have. The 30-year fixed rate has swung meaningfully in recent months, and a new Realtor.com analysis covered by NAR gives buyers an actual framework for planning around that volatility instead of just hoping for the best.
Joel Berner, senior economist at Realtor.com, put the range in blunt terms: "Buyers looking to purchase in one year should be ready for anything between a mortgage rate of about 6% and one of about 8% based on today's rates and historic volatility." That's not a prediction — it's a planning range based on roughly 80% of historical rate movement.
What a Rate Swing Actually Costs
Per a parallel Inman analysis of the same Realtor.com data, here's what rate volatility does to purchasing power for a buyer targeting a $2,000 monthly mortgage payment:
Rate drops 0.75%: +$24,000 buying power - Budget expands to roughly $324,000
Rate rises 0.50%: –$15,000 buying power - Budget drops to roughly $286,000
Rate rises 0.75%: –$21,000 buying power - Budget drops to roughly $279,000
Recommended monthly buffer: $130/month - Based on a $429,500 median home at 10% down and 7% rate
What Buyers Can Actually Control
The encouraging half of this story, is that credit score and down payment size meaningfully offset rate volatility. Borrowers with a 780+ credit score and 30%+ down payment can secure a rate 21 basis points below average. Even a modest credit improvement - moving from the high 600s to 700–720 - can save roughly 5.5 basis points. And shopping multiple lenders instead of accepting the first quote can be worth $174 per month, or roughly $62,000 over the life of a 30-year loan, according to LendingTree research.
Christina's Take for CT Buyers: In a market where Milford, Norwalk, and New Haven homes are routinely selling above asking price, the instinct to wait for a better rate is understandable — and often costly. Building a $130+ monthly buffer into your budget, shopping at least three lenders, and working on credit in the months before you buy puts you in control of the variables that are actually yours to control. The rate itself isn't one of them.
Millennials Have Officially Broken Up With the Formal Dining Room
Every generation redefines what "home" means, and according to realtors interviewed by Real Simple, millennials are rewriting the rulebook on what makes a home desirable. Here are the features losing their grip - and what's replacing them:
- Open floor plans: "Many millennials started questioning an open floor plan at the onset of COVID," says Anne Frewen, agent with the Auerbach + Frewen Team at Coldwell Banker. Working from home exposed exactly how much noise and visual clutter an open layout creates — walls, it turns out, matter.
- Sprawling lawns: Jeff Adams, real estate investing strategist at Home Investors Zone, says millennial buyers are prioritizing "low-maintenance outdoor areas, including patios, composite decking, native landscaping, drought-tolerant plants" over acreage that demands constant mowing and watering.
- Formal dining rooms: Once a luxury entertaining space, the formal dining room is increasingly getting converted into flexible space - a home office, playroom, or guest room depending on the week.
- Wine cellars / wine-focused spaces: "Millennials today are focusing less on wine and more on a wide variety of beverages," Frewen notes. The trade-up: dedicated coffee or beverage bars during renovations and new purchases.
- Whirlpool tubs & jetted tubs: Once a symbol of 1990s luxury, large jetted tubs are now seen as impractical and hard to maintain - increasingly removed in favor of large walk-in showers.
- Media rooms & oversized foyers: Dedicated single-purpose rooms are losing ground to usable, flexible square footage - a trend that tracks directly with affordability pressure pushing buyers to prioritize function over formality.
- Chef-style luxury kitchens (at any cost): Buyers still want a great kitchen - but per agents quoted across multiple 2026 reports, the priority has shifted toward practical upgrades (hardwood or luxury vinyl plank flooring, easy-clean surfaces) over splurge appliances that don't affect daily usability.
The common thread across every one of these shifts, as reported by agents nationwide: millennials are watching total cost of ownership far more closely than previous generations did - asking more direct questions about roof age, HVAC efficiency, insurance costs, and property taxes during showings, rather than getting swept up by photogenic but high-maintenance features.
What This Means for Connecticut Sellers: If a listing's biggest selling point is a formal dining room or a sprawling lawn, it may be time to reframe the marketing. Christina Chorna advises sellers across Milford, Norwalk, and New Haven to highlight flexible square footage, low-maintenance landscaping, and transparent operating costs — roof age, HVAC condition, realistic tax estimates — because that's genuinely what today's buyer pool, millennial or otherwise, is weighing most heavily.
📞 Ready to Talk Strategy for Your Next Move?
Whether it's budgeting around rate swings, understanding what buyers actually want in today's market, or exploring homes currently available across Milford, Norwalk and New Haven, Christina Chorna helps clients navigate the real data behind the headlines. Curious what your home is worth in today's market? Get a free Connecticut home valuation.
Categories
Recent Posts
GET MORE INFORMATION